See the real cost of the loan.
Interest rates have risen in 2026: the ECB raised its key rates in June and September, and the 12-month Euribor is about 3.2%. The average rate on new home loans in August was 3.35% and on new business loans 4.39%. The loan-to-value cap on home loans is now 95% for everyone, and the rules on consumer credit will be reformed on 20.11.2026.
Loan Radar compares the real annual percentage rates and all costs of loans using the same yardstick. The radar does not sell loans, it tells you what they cost.
- Those interested in home, car and consumer loans
- Companies: business loans and financing
Calculator
Calculator
Calculators on their own pages: Loan calculator · Business loan calculator · All calculators
Loan Radar in numbers
Reference rates and key interest rates now
Euribor rates on 5.10.2026 (published with a 24-hour delay), ECB key interest rates from 16.9.2026, and the Interest Act reference rate and default interest rates for 1.7.–31.12.2026.
| Interest | Value | Date |
|---|---|---|
| Euribor 1 week | 2,435 % | 5.10.2026 |
| Euribor 1 month | 2,432 % | 5.10.2026 |
| Euribor 3 months | 2,597 % | 5.10.2026 |
| Euribor 6 months | 2,986 % | 5.10.2026 |
| Euribor 12 months | 3,186 % | 5.10.2026 |
| €STR (euro short-term rate) | 2,438 % | 5.10.2026 |
| ECB deposit rate | 2,50 % | From 16.9.2026 |
| ECB main refinancing operations rate | 2,65 % | From 16.9.2026 |
| ECB marginal lending facility rate | 2,90 % | From 16.9.2026 |
| Reference rate under the Interest Act | 2,5 % | 1.7.–31.12.2026 |
| Default interest (general) | 9,5 % | 1.7.–31.12.2026 |
| Default interest (commercial contracts) | 10,5 % | 1.7.–31.12.2026 |
Source: Bank of Finland (Euribor, reference rate); ECB (key interest rates)
Average loan interest rates in Finland 2026
Average rates on new loans and loan stocks in different months, from the Bank of Finland's monetary and banking statistics.
| Loan | Month | Average interest rate |
|---|---|---|
| New mortgages | January 2026 | 2,84 % |
| New mortgages | May 2026 | 3,17 % |
| New mortgages | July 2026 | 3,28 % |
| New mortgages | August 2026 | 3,35 % |
| New business loans | January 2026 | 3,77 % |
| New business loans | July 2026 | 3,45 % |
| New business loans (excl. housing companies) | August 2026 | 4,39 % |
| Business loan portfolio | August 2026 | 3,82 % |
| Total new household loans | May 2026 | 3,91 % |
| New other consumer credit (excl. vehicle and card credit) | May 2026 | 7,64 % |
| New vehicle loans | May 2026 | 4,08 % |
Source: Bank of Finland, monetary and banking statistics releases 2026
ECB interest rate decisions and the interest rate cap on consumer credit
2026 interest rate decisions, plus the Consumer Protection Act interest rate cap and cost limits.
| Subject | Contents |
|---|---|
| ECB 11.6.2026 | Key rates +0.25 percentage points; deposit rate 2.25% (from 17.6.2026) |
| ECB 23.7.2026 | Rates unchanged; deposit rate 2.25% |
| ECB 10.9.2026 | Key rates +0.25 percentage points; deposit rate 2.50% (from 16.9.2026) |
| Interest rate cap on consumer credit | Reference rate under the Interest Act + 15 percentage points, but no more than 20% (in force since 1.10.2023) |
| Interest rate cap calculated for 1.7.–31.12.2026 | 2,5 % + 15 percentage points = 17,5 % |
| Other credit costs | At most 0,01 % of the loan amount per day, at most 150 € per year |
| Outside the interest rate cap | Credit secured by housing and vehicle hire-purchase |
Source: ECB; Finnish Parliament's Economic Affairs Committee report TaVM 42/2022 vp; Bank of Finland
Consumer credit reform 2026
The EU Consumer Credit Directive (2023/2225) is being implemented by amending the Consumer Protection Act and enacting a new act on intermediaries for certain consumer credits (33/2026). The changes apply to contracts concluded after the entry into force.
| Change | What it means | Effective from |
|---|---|---|
| Distance-selling cancellation function | A financial services contract made online can be cancelled with an easy-to-find function, without a phone call | 19.6.2026 |
| Registration of credit intermediaries | Most providers and lenders of side-line consumer credit must register with the Financial Supervisory Authority (FIN-FSA) (Act 33/2026); the registration provisions take effect on a front-loaded basis | 20.5.2026 |
| Interest-free and fee-free credit | Fall within consumer credit regulation, including many buy now, pay later payment methods; only certain seller payment deferrals are excluded | 20.11.2026 |
| Creditworthiness assessment | The assessment procedure must be documented, and an assessment is also carried out when the credit limit is raised | 20.11.2026 |
| Consequence of non-compliance | If the lender neglects the creditworthiness assessment, the consumer does not have to pay interest or other credit costs (does not apply to minor omissions) | 20.11.2026 |
| Marketing | It must not be implied that credit improves one's standard of living, and the significance of payment defaults for obtaining credit must not be downplayed | 20.11.2026 |
Source: Government proposal HE 120/2025 vp; Finance Committee report TaVM 20/2025 vp; Act 33/2026
Save time with ready-made templates
Free tool available to download with a free account. Larger tools as a one-off purchase, no subscription: files immediately after payment.
 Free tool
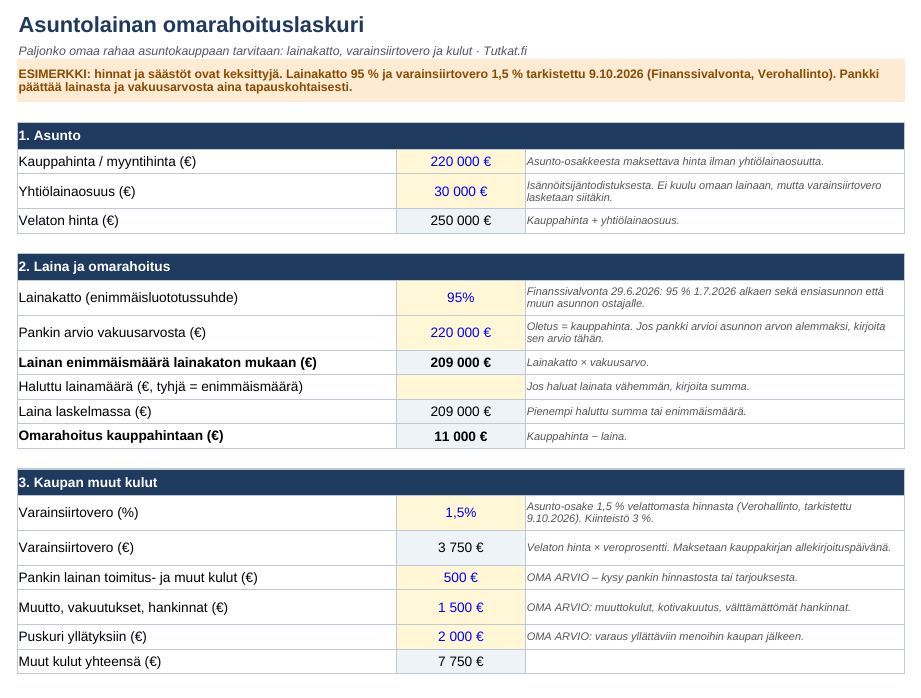
Mortgage down payment calculator
Calculate how much of your own money is needed for a home purchase after the loan-to-value cap, transfer tax and costs.
- Maximum loan amount under the loan-to-value cap (95 %)
- Own financing, transfer tax and other costs of the purchase
- Adequacy of savings and time to goal
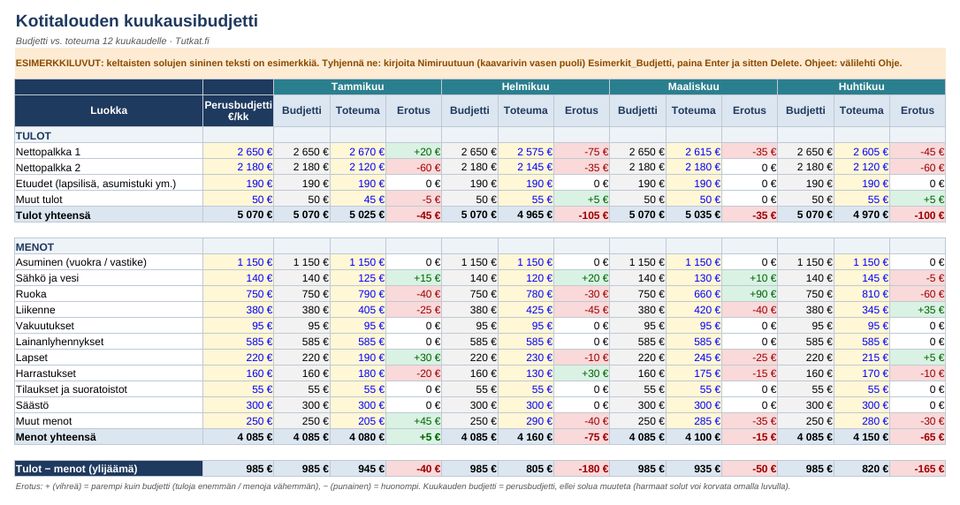
Household budget and debt plan
Monthly budget, savings goals and debt repayment plan.
Households
9,90 € incl. VATBuy 9,90 €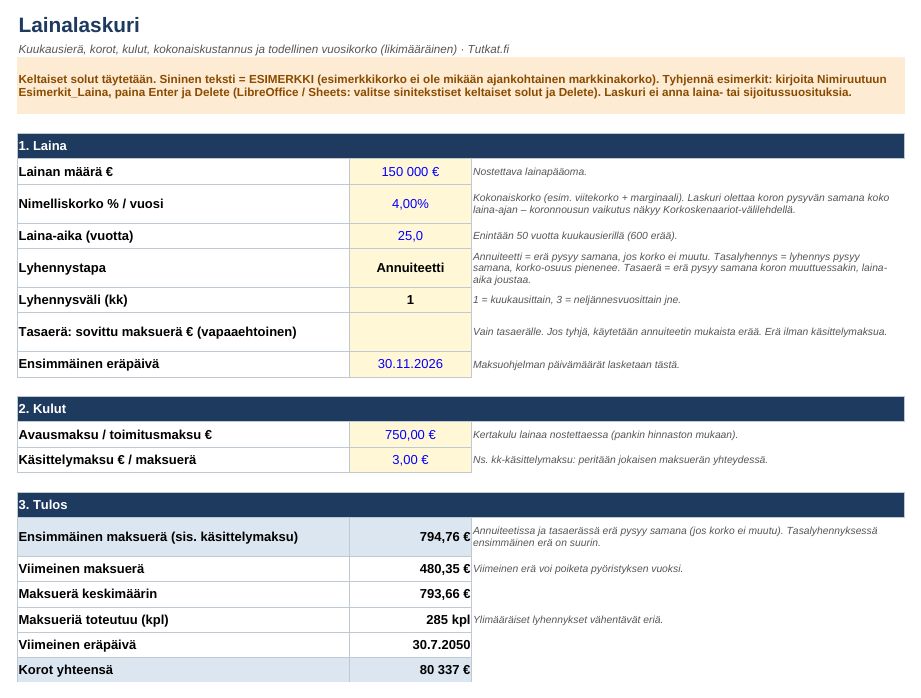
Loan calculator and repayment plan
Monthly instalment, interest and costs, full repayment schedule, interest rate scenarios and comparison of two offers.
For those considering a loan and borrowers
2,90 € incl. VATBuy 2,90 €Read before you decide
Effective annual interest rate and the consumer credit interest rate cap 2026
What does the effective annual interest rate tell you and how does it differ from the nominal rate? The interest rate cap on consumer credit is 17,5 % until the end of 2026. See how to compare.
Read the guide →Positive credit register: what is recorded in it?
Your loans and income are recorded in the positive credit register. See who can view the data, how to check it, and how a credit ban is set up.
Read the guide →Mortgage interest rate 2026: Euribor, margin and loan cap
What makes up a mortgage interest rate? The average rate on new mortgages was 3,35 % in August 2026. See Euribor, margin, loan cap and hedging.
Read the guide →Related topics on other radars
- Housing calculator: what does a home cost in your area? · Housing Radar
- Buffer fund: how much savings should you have for a rainy day? · Money Radar
- Driving cost calculator: petrol or electric car? · Car Radar
- De minimis calculator: how much support can you still receive? · Grants Radar
- Transfer tax 2026: how much, when and how to pay · Housing Radar
Deadlines and dates
Loan Radar reminds its subscribers of these by email.
- Bank of Finland monetary and banking statistics (September)
The average interest rates on new housing and business loans for September 2026 will be published at 10 am.
Source - ECB monetary policy meeting
ECB Governing Council interest rate decision and press conference, Frankfurt.
Source - New rules on consumer credit enter into force
Interest-free and fee-free credit brought within regulation, stricter creditworthiness assessment and a new sanction for failing to carry it out. The Act on Intermediaries of Certain Consumer Credits (33/2026) enters fully into force.
Source - ECB monetary policy meeting
ECB Governing Council interest rate decision and press conference.
Source - New reference rate under the Interest Act enters into force
The reference rate and default interest rates are confirmed every six months; the current 2.5% is valid until 31 Dec 2026. The reference rate also affects the interest rate cap on consumer credit.
Source - ECB monetary policy meeting
ECB Governing Council interest rate decision and press conference.
Source - ECB monetary policy meeting
ECB Governing Council interest rate decision and press conference.
Source - ECB monetary policy meeting
ECB Governing Council interest rate decision and press conference.
Source
No upcoming dates right now.
Frequently asked questions: Loan Radar
What is the 12-month Euribor now?
The 12-month Euribor was 3,186 % on 5.10.2026, compared with 3,323 % on 2.10.2026 (Bank of Finland). Euribor rates are published with a one-day delay, so the figure shows the level of the previous banking day.
What is the average interest rate on a home loan in 2026?
The average interest rate on new mortgages in August 2026 was 3.35%, compared with 2.84% in January 2026 (Bank of Finland). The September figures will be published on 28.10.2026.
When is the ECB's next interest rate decision?
The ECB's next monetary policy meetings are on 29.10.2026 and 17.12.2026. The ECB raised rates in June and September 2026, and the deposit rate has been 2.50% since 16.9.2026.
What is the penalty interest rate in 2026?
The general penalty interest under the Interest Act is 9.5% and the penalty interest for commercial contracts 10.5% for the period 1.7.–31.12.2026, when the reference rate is 2.5%. The new reference rate takes effect on 1.1.2027, and the Finnish Tax Administration (Verohallinto) penalty interest calculator can be used to calculate the amount of interest.
What is the interest rate cap on consumer credit?
The interest rate cap on consumer credit is the Interest Act reference rate + 15 percentage points, but no more than 20 %, so for 1.7.–31.12.2026 the cap is 17.5 %. Other credit costs may be at most 0.01 % of the credit amount per day and at most €150 per year; the cap does not apply to credit secured by a dwelling or to vehicle instalment sales.
What is the annual percentage rate of charge (APR)?
The effective annual interest rate shows the total cost of credit – interest and all mandatory costs – as an annual percentage. It is the best figure for comparing different loan offers, because the nominal interest rate alone does not show opening fees or account management fees. In marketing consumer credit, the effective annual interest rate must be stated using an example.
What is the positive credit register?
The positive credit register was introduced in Finland in April 2024. It collects information on people's loans and income, and a lender must check it before granting consumer credit. The register is maintained by the Incomes Register Unit of the Finnish Tax Administration (Verohallinto), and you can view your own data online free of charge.
What does a bank look at when granting a business loan?
A bank assesses above all the company's ability to service the loan from its cash flow: the ratio of operating profit (EBITDA) to debt service costs, collateral, equity ratio and payment history. Prepare for the loan negotiation the latest financial statements, the current year's result and a 12-month cash flow forecast. An SME can apply for a Finnvera guarantee alongside a bank loan.
What is the loan cap for home loans in 2026?
The maximum loan-to-collateral ratio of a mortgage is 95 % of the fair value of the collateral for all borrowers. The Financial Supervisory Authority raised the cap for buyers other than first-time buyers from 90 % to 95 % on 30.6.2026 and decided on 30.9.2026 to continue the relaxation. The cap for first-time buyers was already 95 %.
For how long can a home loan be taken?
After the legislative change that entered into force in June 2026, the maximum term of a new home loan is 40 years, compared with 30 years previously. A longer term reduces the monthly instalment but increases the total amount of interest paid.
What changes in consumer credit on 20.11.2026?
Interest-free and fee-free credit, such as many buy now, pay later payment methods, will come under consumer credit regulation. The lender must document the creditworthiness assessment and carry it out also when raising a credit limit. If the assessment is neglected, the consumer does not have to pay interest or other credit costs.
What does Act 33/2026 on credit intermediaries mean for a company?
The Act on Certain Consumer Credit Intermediaries obliges most part-time consumer credit intermediaries and lenders to register with the Financial Supervisory Authority (FIN-FSA). The provisions on registration and reliability assessment entered into force on 20.5.2026 and the Act as a whole on 20.11.2026. Certain SMEs are exempt from the registration obligation, so check your own situation with FIN-FSA.
How to use the information
- Euribor rates are published with a one-day delay, so today's figure shows the level of the previous banking day.
- The interest rate cap on consumer credit is calculated as follows: Interest Act reference rate + 15 percentage points, but no more than 20 %. In late 2026 the cap is 17.5 %.
- In business-to-business transactions, the late-payment interest rate for 1.7.–31.12.2026 is 10,5 % in total; the new reference rate takes effect on 1.1.2027.
- Most Finnish loans are tied to Euribor, so the loan interest rate only changes on the rate change date according to the reference rate.
- The maximum mortgage is now 95 % of the fair value of the collateral for all buyers. You therefore need at least 5 % of your own funding or additional collateral.
- A 40-year loan term lowers the monthly instalment, but clearly more interest accrues over the whole period. Calculate both the 25- and 40-year options before deciding.
- From 20.11.2026, interest-free and fee-free credits too, such as many buy now, pay later payment methods, are consumer credits. Track their due dates like any other loan.
- If debts are getting out of control, seek help in good time: the financial and debt counselling of the legal aid offices and Takuusäätiö offer free advice.
- If your business intermediates or offers consumer credit as a side activity, for example instalment payment in an online shop, check with the Financial Supervisory Authority (Finanssivalvonta) whether the registration obligation under Act 33/2026 applies to you.
- The average interest rate on new business loans in August 2026 was 4.39%, but 3.82% for the entire loan stock. Tender your new loan and negotiate the margin, because the reference rate is the same for everyone.
Useful links
Get the Loan Radar digest by email
Every Monday or once a month: the most important figures and the next deadlines. Free of charge, and you can cancel at any time.
Related radars
Sources (20)
- ECB: Monetary policy decisions 10.9.2026 (STT Info)
- ECB: Monetary policy decisions 11.6.2026
- ECB: Monetary policy decisions 23.7.2026
- ECB: Governing Council meeting calendar
- Bank of Finland: Growth in the corporate loan stock accelerated in summer 2026 (28.9.2026)
- Bank of Finland: The number of housing loans with longer repayment periods has increased (28.8.2026)
- Bank of Finland: Household loan rates rose in May 2026 (30.6.2026)
- Suomen Pankki: Average interest rate on housing loans has levelled off (27.2.2026)
- Bank of Finland: Reference rate under the Interest Act and default interest 1.7.–31.12.2026
- Parliament: Economic Affairs Committee report TaVM 42/2022 vp (interest rate cap)
- Verkkouutiset: Legislative change affects online shopping and consumer credit (2.8.2023)
- Bank of Finland: Euribor rates (5.10.2026)
- Financial Supervisory Authority: Macroprudential decision, home loan cap 95 % for all (30.6.2026)
- Financial Supervisory Authority: Macroprudential decision, eased loan cap remains (30.9.2026)
- Finnish Government: Reform of housing finance regulation (7.5.2026)
- Statistics Finland: The amount of enforcement debts grew in 2025 (14.4.2026)
- Edilex: HE 120/2025 vp implementation of the Consumer Credit Directive
- Edilex: Economic Affairs Committee report TaVM 20/2025 vp
- Finlex: Act on certain consumer credit intermediaries 33/2026
- KPMG: Changes in the Consumer Protection Act arising from the Consumer Credit Directive
The information has been compiled from public sources on 6.10.2026. Always check the current terms from the original source. The information is not investment, loan or legal advice.